

Since March 2026, Core Natural Resources has been in a holding pattern, posting a small loss of 0.6% while floating around $97.06. The stock also fell short of the S&P 500’s 13.3% gain during that period.
Is now the time to buy CNR? Find out in our full research report, it’s free.
Why Does CNR Stock Spark Debate?
Tracing its origins to 1864 and operating some mines southwest of Pittsburgh, Core Natural Resources (NYSE:CNR) mines and exports metallurgical coal used in steelmaking and thermal coal for power generation.
Two Things to Like:
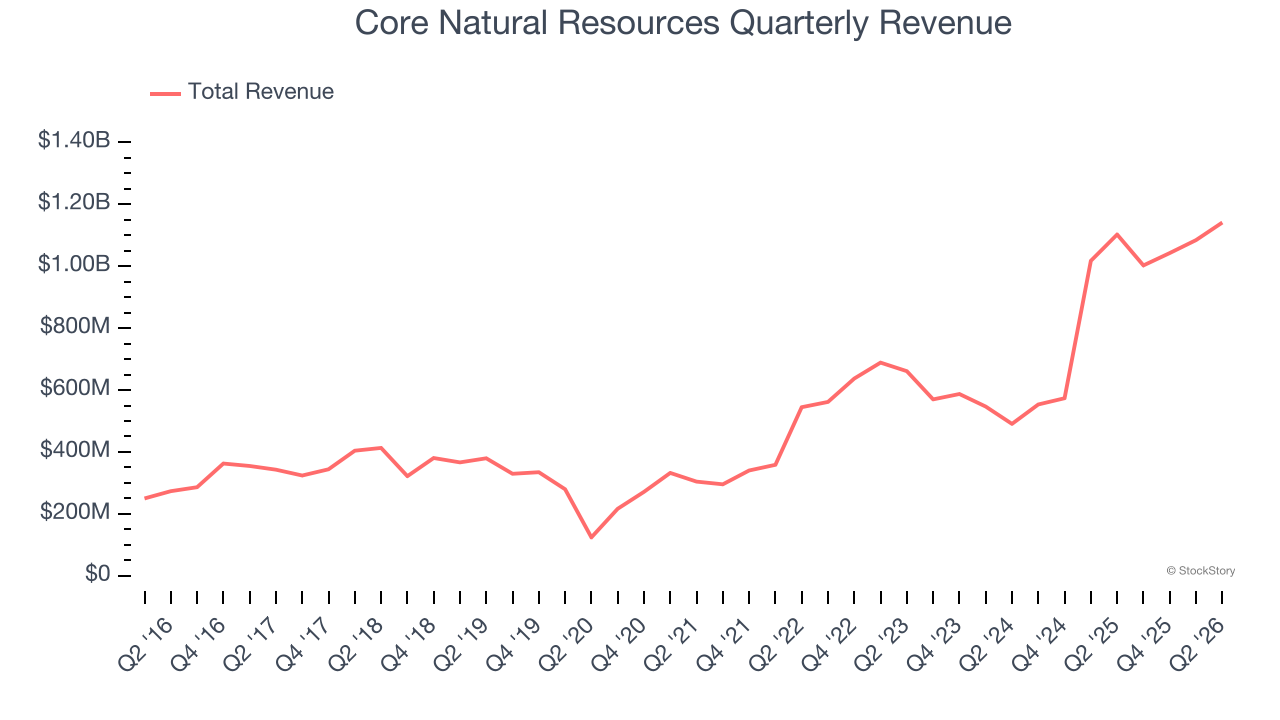
1. Skyrocketing Revenue Shows Strong Momentum
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Thankfully, Core Natural Resources’s 30.6% annualized revenue growth over the last five years was incredible. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Economies of Scale Give It Negotiating Leverage with Suppliers
The size of the revenue base is a way to assess topline, and it tells an investor whether an Energy producer has crossed the line between being a more vulnerable commodity taker and a durable operating platform. Scaled businesses tend to produce and generate revenue from many wells, pads, takeaway routes, and geographies, not just a single field or drilling program.
Core Natural Resources’s $4.27 billion of revenue in the last year is mid-sized for the industry.
One Reason to Be Careful:
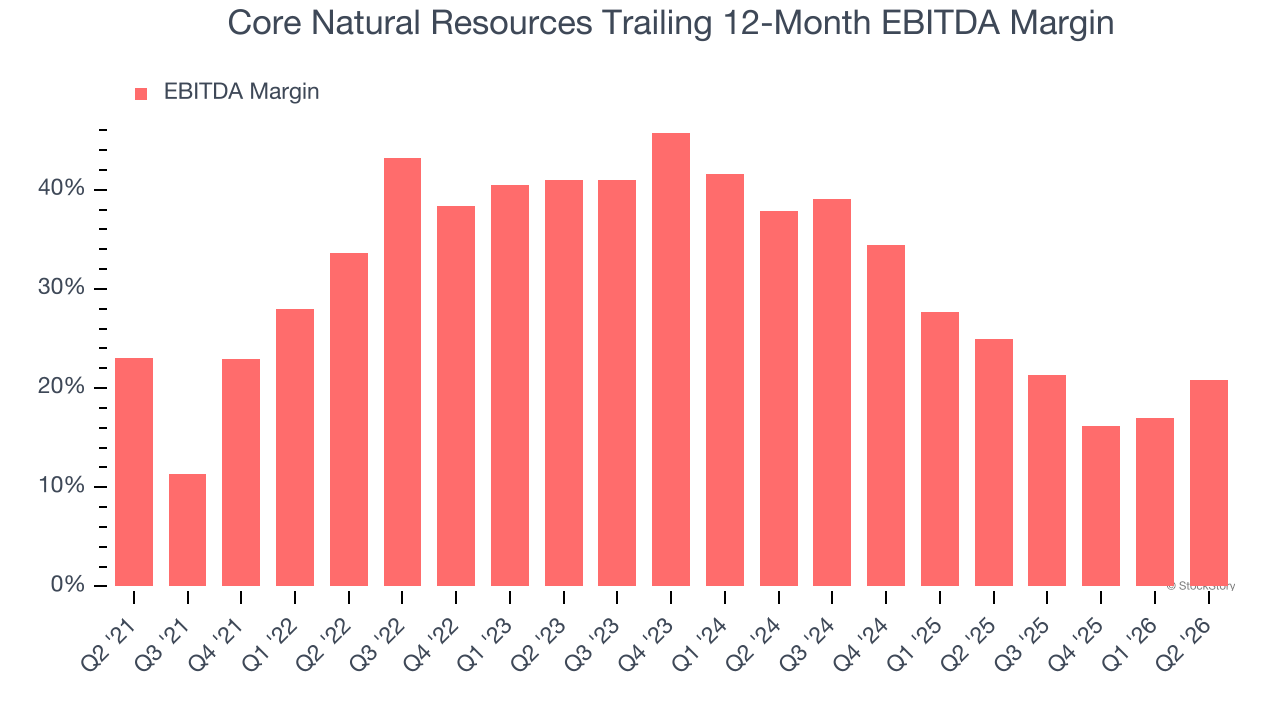
Shrinking EBITDA Margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Looking at the trend in its profitability, Core Natural Resources’s EBITDA margin decreased by 12.8 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Core Natural Resources’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its EBITDA margin for the trailing 12 months was 20.8%.
Final Judgment
Core Natural Resources’s positive characteristics outweigh the negatives. With its shares underperforming the market lately, the stock trades at 22.7× forward P/E (or $97.06 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.